A phone can be affordable to buy but expensive to own, or easy to finance but difficult to repay. This section separates three questions: what the phone costs, whether credit is involved and whether the commitment remains manageable across the full term.
Choose the route that matches your decision
| Your question | Guide | Main output |
|---|---|---|
| How does phone finance work? | Phone Finance and Credit | Agreement map, lender, credit cost and ownership |
| What happens during an application? | Credit Checks for Phone Contracts | Hard and soft searches, preparation and declined applications |
| Can finance affect my credit file? | How Phone Finance Affects Your Credit Score | Applications, payment history and corrections |
| Can I safely carry the payment? | Phone Finance: Can You Afford It? | Full-term budget and stress test |
| I have a limited purchase budget | Budget Phone Buying | Routes to a dependable lower-cost handset |
Do not start with “What monthly payment can I get?”
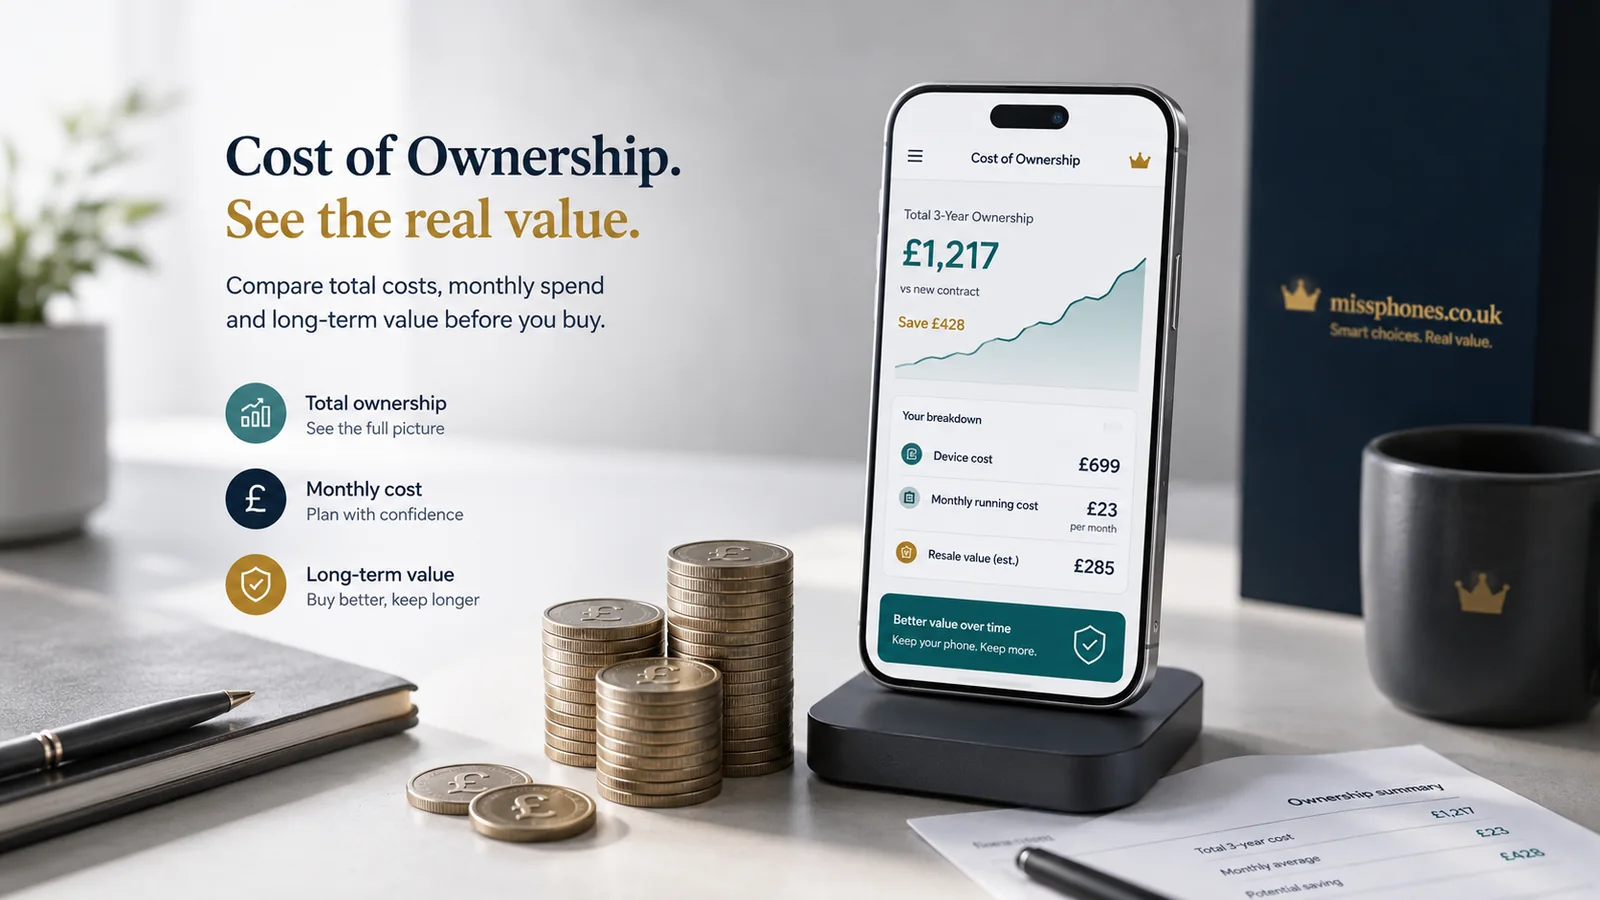
Start with the phone you need, the years you expect to keep it and the maximum total ownership cost. A long term can reduce the monthly figure while increasing the period during which your income, bills or circumstances may change.
Before applying, write down:
- cash price of the exact phone;
- amount of credit and any interest or fees;
- total amount payable;
- airtime cost and scheduled rises;
- insurance and optional extras;
- early-settlement and missed-payment consequences;
- expected resale value, shown separately rather than treated as guaranteed.
Credit approval is not an affordability certificate
A provider's decision reflects its own risk and creditworthiness process. Acceptance does not prove that the payment is comfortable for your household, and rejection does not establish a universal verdict on your finances. Use your own budget and the specific reason available from the provider.
Lower-cost routes belong in the comparison
If the intended phone is not comfortably affordable, compare a previous-generation model, a verified refurbished phone, a simpler new handset or keeping the current phone after a sensible repair. The goal is reliable ownership, not approval for the largest available device plan.
Reference points for current UK rules: Finance and Affordability
- FCA: creditworthiness and affordability
- ICO: credit reference agencies and credit files
- MoneyHelper: checking your credit report
Checks that matter for Finance and Affordability
- Full commitment:add upfront charges and every required monthly payment over the minimum term, including any clearly stated scheduled price changes before applying it to this particular case.
- Device and airtime are different costs:separate what you are paying for the handset from network service where possible, with the finance affordability case in mind. For this page on Finance and Affordability, this makes a contract comparable with an outright phone plus SIM-only route.
- Exit and flexibility:check minimum term, early-exit consequences, upgrade mechanics and what happens to the handset at the end, with the finance affordability case in mind. In this decision, a low monthly figure can hide a long inflexible commitment when assessing Finance and Affordability.
- Coverage before price:a cheap tariff has little value if it does not work where you regularly need it, with the finance affordability case in mind. For this scenario, use current coverage information and, where practical, real-world experience in the places that matter when assessing Finance and Affordability.